College Connect
Preparing your experience...
Preparing your experience...
Need help? 👋
We're here to help you
Looking for the right college, course or admission guidance? Choose an option below.
Managing money during college can be challenging when you have to balance food, transport, accommodation, study materials and personal expenses. Learn how to build a realistic monthly budget, track spending, save money and prepare for unexpected costs.
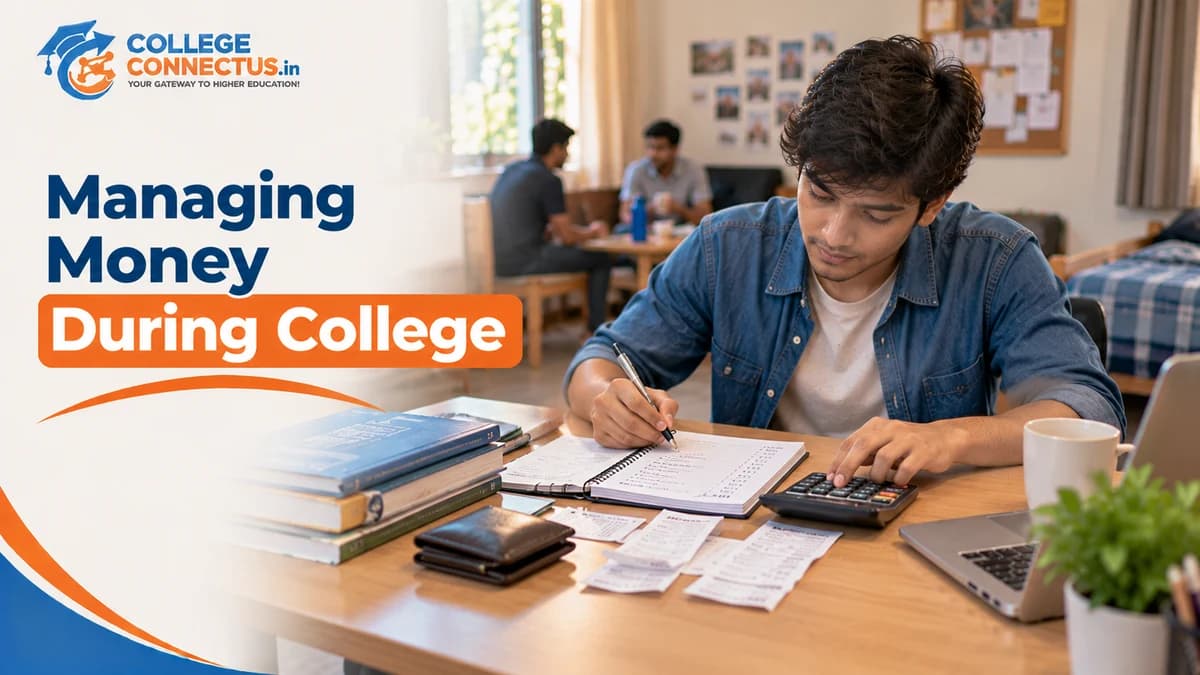
College is an important stage of life, but it can also be the first time many students have to manage their own money.
You may need to pay for food, transport, accommodation, mobile data, books, stationery, subscriptions and social activities. If you live away from home, you may also need to manage hostel charges, laundry, travel home and other everyday expenses.
Without a plan, small purchases can add up quickly. You might have enough money at the beginning of the month but struggle to cover essential expenses near the end.
The solution is not necessarily to stop spending on everything you enjoy. It is to understand where your money goes and make decisions that fit your available resources.
A student budget is a plan for allocating your available money across essential expenses, personal spending, savings and unexpected costs. It helps you make informed choices rather than relying on guesswork.
This guide explains how to create a monthly budget as a college student in India, track expenses, manage hostel and living costs, save where possible and avoid common financial mistakes.
A monthly budget is a simple record of how much money you expect to receive, how much you plan to spend and how much you want to keep aside.
Your available money might come from family support, a scholarship, a stipend, permitted part-time work or personal savings. The amount and reliability of these sources will vary from student to student.
Your expenses may include:
Accommodation and hostel charges.
Food and groceries.
Local transport.
Mobile and internet costs.
Books, stationery and printing.
Laundry and personal care.
Academic activities and examination-related costs.
Social activities and entertainment.
Travel home.
Emergency expenses.
Not every student will have all these expenses. For example, a student living with family may not pay hostel charges, while a student living in a residential college may have accommodation and meal costs included in a fee package.
Your budget should reflect your actual circumstances rather than a generic spending formula.
Learning to manage money can help you make better decisions throughout your education.
You may know your major expenses but overlook smaller purchases such as snacks, delivery charges, transport upgrades or subscriptions.
Recording expenses helps you understand how much these purchases cost over an entire month.
When you know which expenses must be paid and when they are due, you can plan ahead instead of being surprised by recurring bills.
This is especially useful when you have examination fees, project costs or travel expenses during a particular month.
A budget can help you reserve money for important academic requirements, such as books, internet access, project materials or examination-related expenses.
It can also help you compare optional purchases against your educational priorities.
Budgeting gives you a clearer picture of what you can afford.
You can decide whether to join an activity, purchase a course, travel home or buy a new device based on your available resources rather than pressure from friends.
Unexpected expenses may include a medical consultation, an urgent journey home, a device repair or an additional academic requirement.
When possible, setting aside even a small amount can help you prepare for these situations. If your income barely covers essential expenses, focus first on understanding your costs and discussing necessary support with your family or college.
Before planning your spending, determine how much money you can realistically use.
Make a list of your regular and occasional sources of money.
For example:
Source | Monthly amount | Reliability |
|---|---|---|
Family support | ₹6,000 | Regular, if agreed |
Scholarship support | Varies by payment schedule | May not arrive monthly |
Internship stipend | ₹3,000 | Depends on the internship terms |
Personal savings | Varies | Limited and not necessarily recurring |
These figures are illustrative only. They are not estimates of what every student receives.
A scholarship may be paid once per semester or academic year rather than monthly. A stipend may end when an internship finishes. Money received for a specific academic expense may also need to be reserved for that purpose.
Avoid treating every occasional payment as guaranteed monthly income.
If you receive a larger payment, work out how much needs to cover upcoming expenses before deciding how much is available for discretionary spending.
For a practical budget, use your dependable monthly funds as the starting point.
If your family provides a fixed monthly allowance, confirm what it is expected to cover. If the amount changes, plan using a conservative estimate and discuss how unexpected essential expenses will be handled.
The aim is to build a budget around realistic resources rather than an optimistic assumption.
Essential expenses are the costs you need to cover to maintain your accommodation, wellbeing and education.
The exact list depends on your living arrangements.
Possible costs include hostel fees, rent, utilities or contributions towards shared household expenses.
Some colleges collect accommodation and mess charges in advance. If so, divide those costs by the number of months they cover to understand their equivalent monthly cost.
For example, if an accommodation charge covers a full semester, do not treat the entire amount as a normal weekly expense. Record when the payment is actually due and plan for it ahead of time.
Food costs may include mess charges, groceries, drinking water and occasional meals outside your regular arrangement.
If your accommodation includes meals, record that cost separately from additional food purchases.
Include regular commuting, public transport, shared rides or other necessary travel.
If you travel home during holidays, estimate those costs separately so they do not unexpectedly consume the money needed for your normal monthly expenses.
These may include:
Books and reference materials.
Printing and photocopying.
Stationery.
Project supplies.
Laboratory or practical materials where applicable.
Examination or application fees.
Internet access needed for coursework.
Some academic costs occur only once or twice per semester. Record the expected payment date rather than assuming every expense occurs every month.
Mobile recharges, internet plans, toiletries, laundry and basic personal care may be recurring costs.
Review the actual amount you spend instead of relying on a rough guess.
Once you have listed your expenses, identify which ones are essential and which are optional.
A need is an expense that supports an important requirement, such as food, accommodation, transport to college or necessary academic materials.
A want is an optional purchase or activity that you would enjoy but could postpone or reduce if money is limited.
Some expenses depend on the circumstances. For example, a paid software subscription may be optional for one student but necessary for a particular course or project.
Use the following questions to evaluate a purchase:
Do I need this for education, health, accommodation or another important responsibility?
Do I already have something that serves the same purpose?
Can I borrow, share or access it through my college?
Is there a lower-cost alternative that meets the same need?
Will buying it now affect another important expense?
This approach does not mean you should never spend money on entertainment. It means you should understand the trade-offs before making a decision.
After identifying your available money and essential costs, create a simple monthly budget.
Here is an illustrative example for a student whose accommodation is already covered separately.
Expense category | Planned amount |
|---|---|
Food and additional meals | ₹2,000 |
Local transport | ₹800 |
Mobile and internet | ₹400 |
Books, stationery and printing | ₹500 |
Laundry and personal care | ₹500 |
Social activities and entertainment | ₹600 |
Travel and irregular expenses fund | ₹700 |
Emergency savings, if affordable | ₹500 |
Total planned allocation | ₹6,000 |
This is only a mathematical example of how a ₹6,000 allowance could be allocated. Actual costs can be significantly different depending on the city, accommodation, meal arrangements, travel requirements and course.
If your accommodation and meals are not covered separately, you must include those costs before deciding how much is available for other categories.
Do not force the numbers to fit an unrealistic budget.
Instead:
Identify which costs are fixed and which may be reduced.
Check whether your college provides subsidised facilities or student assistance.
Review available scholarships and their eligibility conditions.
Discuss essential expenses with your family or another trusted support person.
Consider safe and legitimate ways to increase available resources, where practical.
Avoid relying on high-cost borrowing to fund ordinary recurring expenses without understanding the repayment obligations.
A budget is a planning tool, not a reason to neglect essential needs.
Creating a budget is only the first step. You also need to compare your plan with what you actually spend.
Choose a tracking method that is simple enough to maintain.
A spreadsheet can record the date, expense category, amount and payment method.
Example:
Date | Expense | Category | Amount |
|---|---|---|---|
2 November | Bus fare | Transport | ₹40 |
3 November | Notebook | Academic | ₹120 |
4 November | Laundry | Personal care | ₹80 |
5 November | Snacks | Food | ₹60 |
These entries are illustrative examples, not actual spending data.
At the end of each week, total your expenses by category and compare them with your plan.
If you prefer writing by hand, record purchases in a notebook.
You do not need a complicated format. Date, description, category and amount are usually enough to start.
A budgeting application may help you categorise spending and review totals. Before choosing one, check its privacy policy, permissions and data-handling practices.
You do not need to connect your bank account or share sensitive financial information with an app just to maintain a basic budget.
A weekly review can help you identify problems before the end of the month.
Ask yourself:
Which category is using more money than expected?
Were the additional expenses necessary?
Are there upcoming payments I have not planned for?
Is the remaining money sufficient for the rest of the month?
Does my budget need to change?
Adjust your plan when circumstances change. The objective is to understand your spending, not to create a perfect record on the first attempt.
You may be able to reduce some costs without sacrificing essential needs.
If you have access to a college mess, compare its cost and meal arrangements with the alternatives available to you.
Students living independently may be able to prepare simple meals when facilities, time and safety permit.
Do not compromise on adequate food simply to meet an unrealistic savings target.
Before purchasing a textbook, check whether the college library has a copy or whether a legitimate digital edition is available through your institution.
Libraries may also provide study spaces and access to academic resources that would otherwise cost money.
Our guide on how to use a college library effectively in India explains ways to make better use of library resources.
If public transport is practical and safe for your route, compare its cost with other options.
Check whether your institution or local transport provider offers eligible student concessions or passes. Conditions vary, so verify the applicable rules before relying on a discount.
Review your actual data use and choose a plan that meets your academic and communication needs.
Avoid paying for several overlapping services that you rarely use.
Where permitted and practical, consider borrowing books, buying used copies or sharing appropriate reference materials with classmates.
For course-specific requirements, confirm that the edition or material is acceptable before purchasing a cheaper alternative.
For non-urgent items, make a list and compare prices before purchasing.
You can also wait a day before making a discretionary purchase to decide whether it is still important.
The goal is not to eliminate every small pleasure. It is to spend deliberately.
One of the most common budgeting problems is forgetting expenses that do not occur every month.
Examples include:
Semester fees.
Examination charges.
Project materials.
Laboratory-related expenses.
Travel home during holidays.
Laptop or phone repairs.
Books required for a new semester.
Internship-related travel.
College events or required equipment.
Create a separate list of expected irregular costs.
If an expense is known in advance, estimate its amount and due date. If possible, set aside a portion of your available money over time.
For example, if you expect a ₹2,400 expense in four months, setting aside ₹600 per month would cover it, provided that amount is affordable within your budget.
If you cannot set money aside every month, record the deadline and discuss how the expense will be covered before it becomes urgent.
An emergency fund is intended for unexpected essential costs, not routine discretionary purchases.
Even a modest reserve may be useful if you can afford to build one. If your current resources cover only essential expenses, do not feel pressured to save an arbitrary percentage. Focus first on meeting your needs and finding appropriate support.
Scholarships and financial assistance may reduce the cost of education for eligible students.
Depending on the programme, support may be based on academic performance, household income, social category, disability, location, field of study or other eligibility conditions.
However, eligibility, application procedures, payment schedules and permitted uses vary by scheme.
Check the official website of the relevant scholarship provider.
Read the current eligibility requirements carefully.
Confirm the application deadline.
Prepare the required documents.
Submit accurate information.
Save the application reference and confirmation.
Track the application through the official process.
Do not assume that an application guarantees payment. Avoid budgeting around an unconfirmed scholarship award, particularly if the money is needed for an immediate bill.
For a broader explanation of financial support, read our guide on college scholarships in India: types, eligibility, documents and application process.
College students may encounter credit cards, short-term loans, instalment plans and buy-now-pay-later services while shopping online.
These products can make purchases appear more affordable because the full payment is delayed. However, delayed payment does not remove the cost.
Before borrowing, understand:
The total amount you must repay.
The interest rate and applicable fees.
The repayment schedule.
The consequences of missing a payment.
Whether the repayment depends on income you can reliably expect.
Whether the purchase is necessary.
Do not borrow simply to maintain a lifestyle that your current budget cannot support.
If you need financing for education, compare legitimate options carefully and review the full terms with a trusted adult or qualified adviser when appropriate.
Our guide on education loans for college students in India explains important considerations around education financing.
College often involves social activities, celebrations, food outings and group purchases. It can be uncomfortable to say no when friends suggest an activity that does not fit your budget.
Remember that your financial circumstances may differ from those of your classmates.
You can maintain friendships without agreeing to every expense.
Try practical alternatives:
Suggest a lower-cost activity.
Meet friends on campus instead of at an expensive venue.
Decide your spending limit before going out.
Explain politely that you are managing your monthly budget.
Avoid borrowing money merely to keep up with other people's purchases.
You do not need to disclose your family's finances or personal circumstances to justify every decision.
A budget should help you participate in activities you value while maintaining control over essential expenses.
If you estimate expenses without recording them, you may underestimate how much you actually spend.
Track your spending for a few weeks to develop a more accurate picture.
Semester fees, travel and academic purchases can disrupt an otherwise reasonable monthly plan.
Record expected costs and deadlines separately.
Money intended for fees, rent or another specific purpose should not automatically be treated as discretionary income.
Reserve it for the obligation it is meant to cover.
A budget that leaves no room for ordinary variation can be difficult to maintain.
Use realistic estimates and adjust them as you learn more about your expenses.
Subscriptions, delivery fees and other repeated charges can add up over time.
Review recurring payments and cancel services you no longer need, where appropriate.
Repeatedly borrowing to pay for ordinary discretionary expenses can create financial pressure.
Review the underlying budget and seek support if your available resources do not cover essential costs.
Be cautious about sharing banking credentials, one-time passwords, account screenshots or identity documents with unverified people or services.
Use official payment channels and protect your financial accounts.
You can copy the following template into a spreadsheet or notebook.
Budget item | Planned amount | Actual amount | Difference |
|---|---|---|---|
Total available money | ₹_____ | ₹_____ | ₹_____ |
Accommodation | ₹_____ | ₹_____ | ₹_____ |
Food | ₹_____ | ₹_____ | ₹_____ |
Transport | ₹_____ | ₹_____ | ₹_____ |
Academic expenses | ₹_____ | ₹_____ | ₹_____ |
Mobile and internet | ₹_____ | ₹_____ | ₹_____ |
Personal care and laundry | ₹_____ | ₹_____ | ₹_____ |
Social activities | ₹_____ | ₹_____ | ₹_____ |
Irregular expenses | ₹_____ | ₹_____ | ₹_____ |
Savings, if affordable | ₹_____ | ₹_____ | ₹_____ |
Remaining balance | ₹_____ | ₹_____ | ₹_____ |
Calculate the remaining balance by subtracting actual spending and any money reserved for upcoming obligations from the money available.
The difference between planned and actual spending shows where you may need to adjust your estimates or spending decisions.
Review the template at the end of each month and use what you learn to plan the next one.
There is no single amount that suits every student. Monthly costs depend on the city, accommodation, food arrangements, transport, course requirements and personal circumstances. List your actual expenses and build a budget around your available resources.
Start by understanding what your hostel fees include. Review additional food purchases, transport, subscriptions and optional spending. Use college facilities where appropriate and plan for travel and academic expenses in advance.
Saving can be helpful when affordable, but essential needs come first. If your available money barely covers necessary expenses, focus on accurate budgeting and exploring appropriate financial support rather than forcing yourself to save an unrealistic amount.
Neither is automatically better. A spreadsheet provides flexibility, while an app may make tracking more convenient. Choose a method you can maintain consistently and review the privacy implications before sharing financial information with an app.
First, understand the scholarship's terms and whether the money is intended for specific educational expenses. Record upcoming fees and essential costs, reserve money for obligations and avoid treating unconfirmed future payments as guaranteed income.
Identify the shortfall and distinguish essential costs from optional spending. Review possible cost reductions, check college assistance and scholarship options, and discuss necessary expenses with your family or another trusted support person. Avoid taking on costly debt without understanding the consequences.
Credit is not free money. Before borrowing, understand the interest, fees, repayment schedule and consequences of missed payments. Consider whether the expense is necessary and whether repayment is realistically affordable.
Managing money during college does not require advanced financial knowledge or a complicated application. It starts with understanding how much money you have, identifying your essential expenses and tracking where your money goes.
Create a realistic monthly budget, prepare for semester-based costs, review your spending regularly and make adjustments when circumstances change.
Use available educational resources, research financial assistance carefully and be cautious with credit and online payment requests.
Most importantly, remember that students have different financial circumstances. Your budget should reflect your real needs and available resources, not someone else's lifestyle.
A good student budget is not about spending as little as possible. It is about making informed decisions so your money supports your education, wellbeing and priorities.
Explore expert articles, admission guides, career tips, education news, exam preparation, and everything you need to make informed academic decisions.